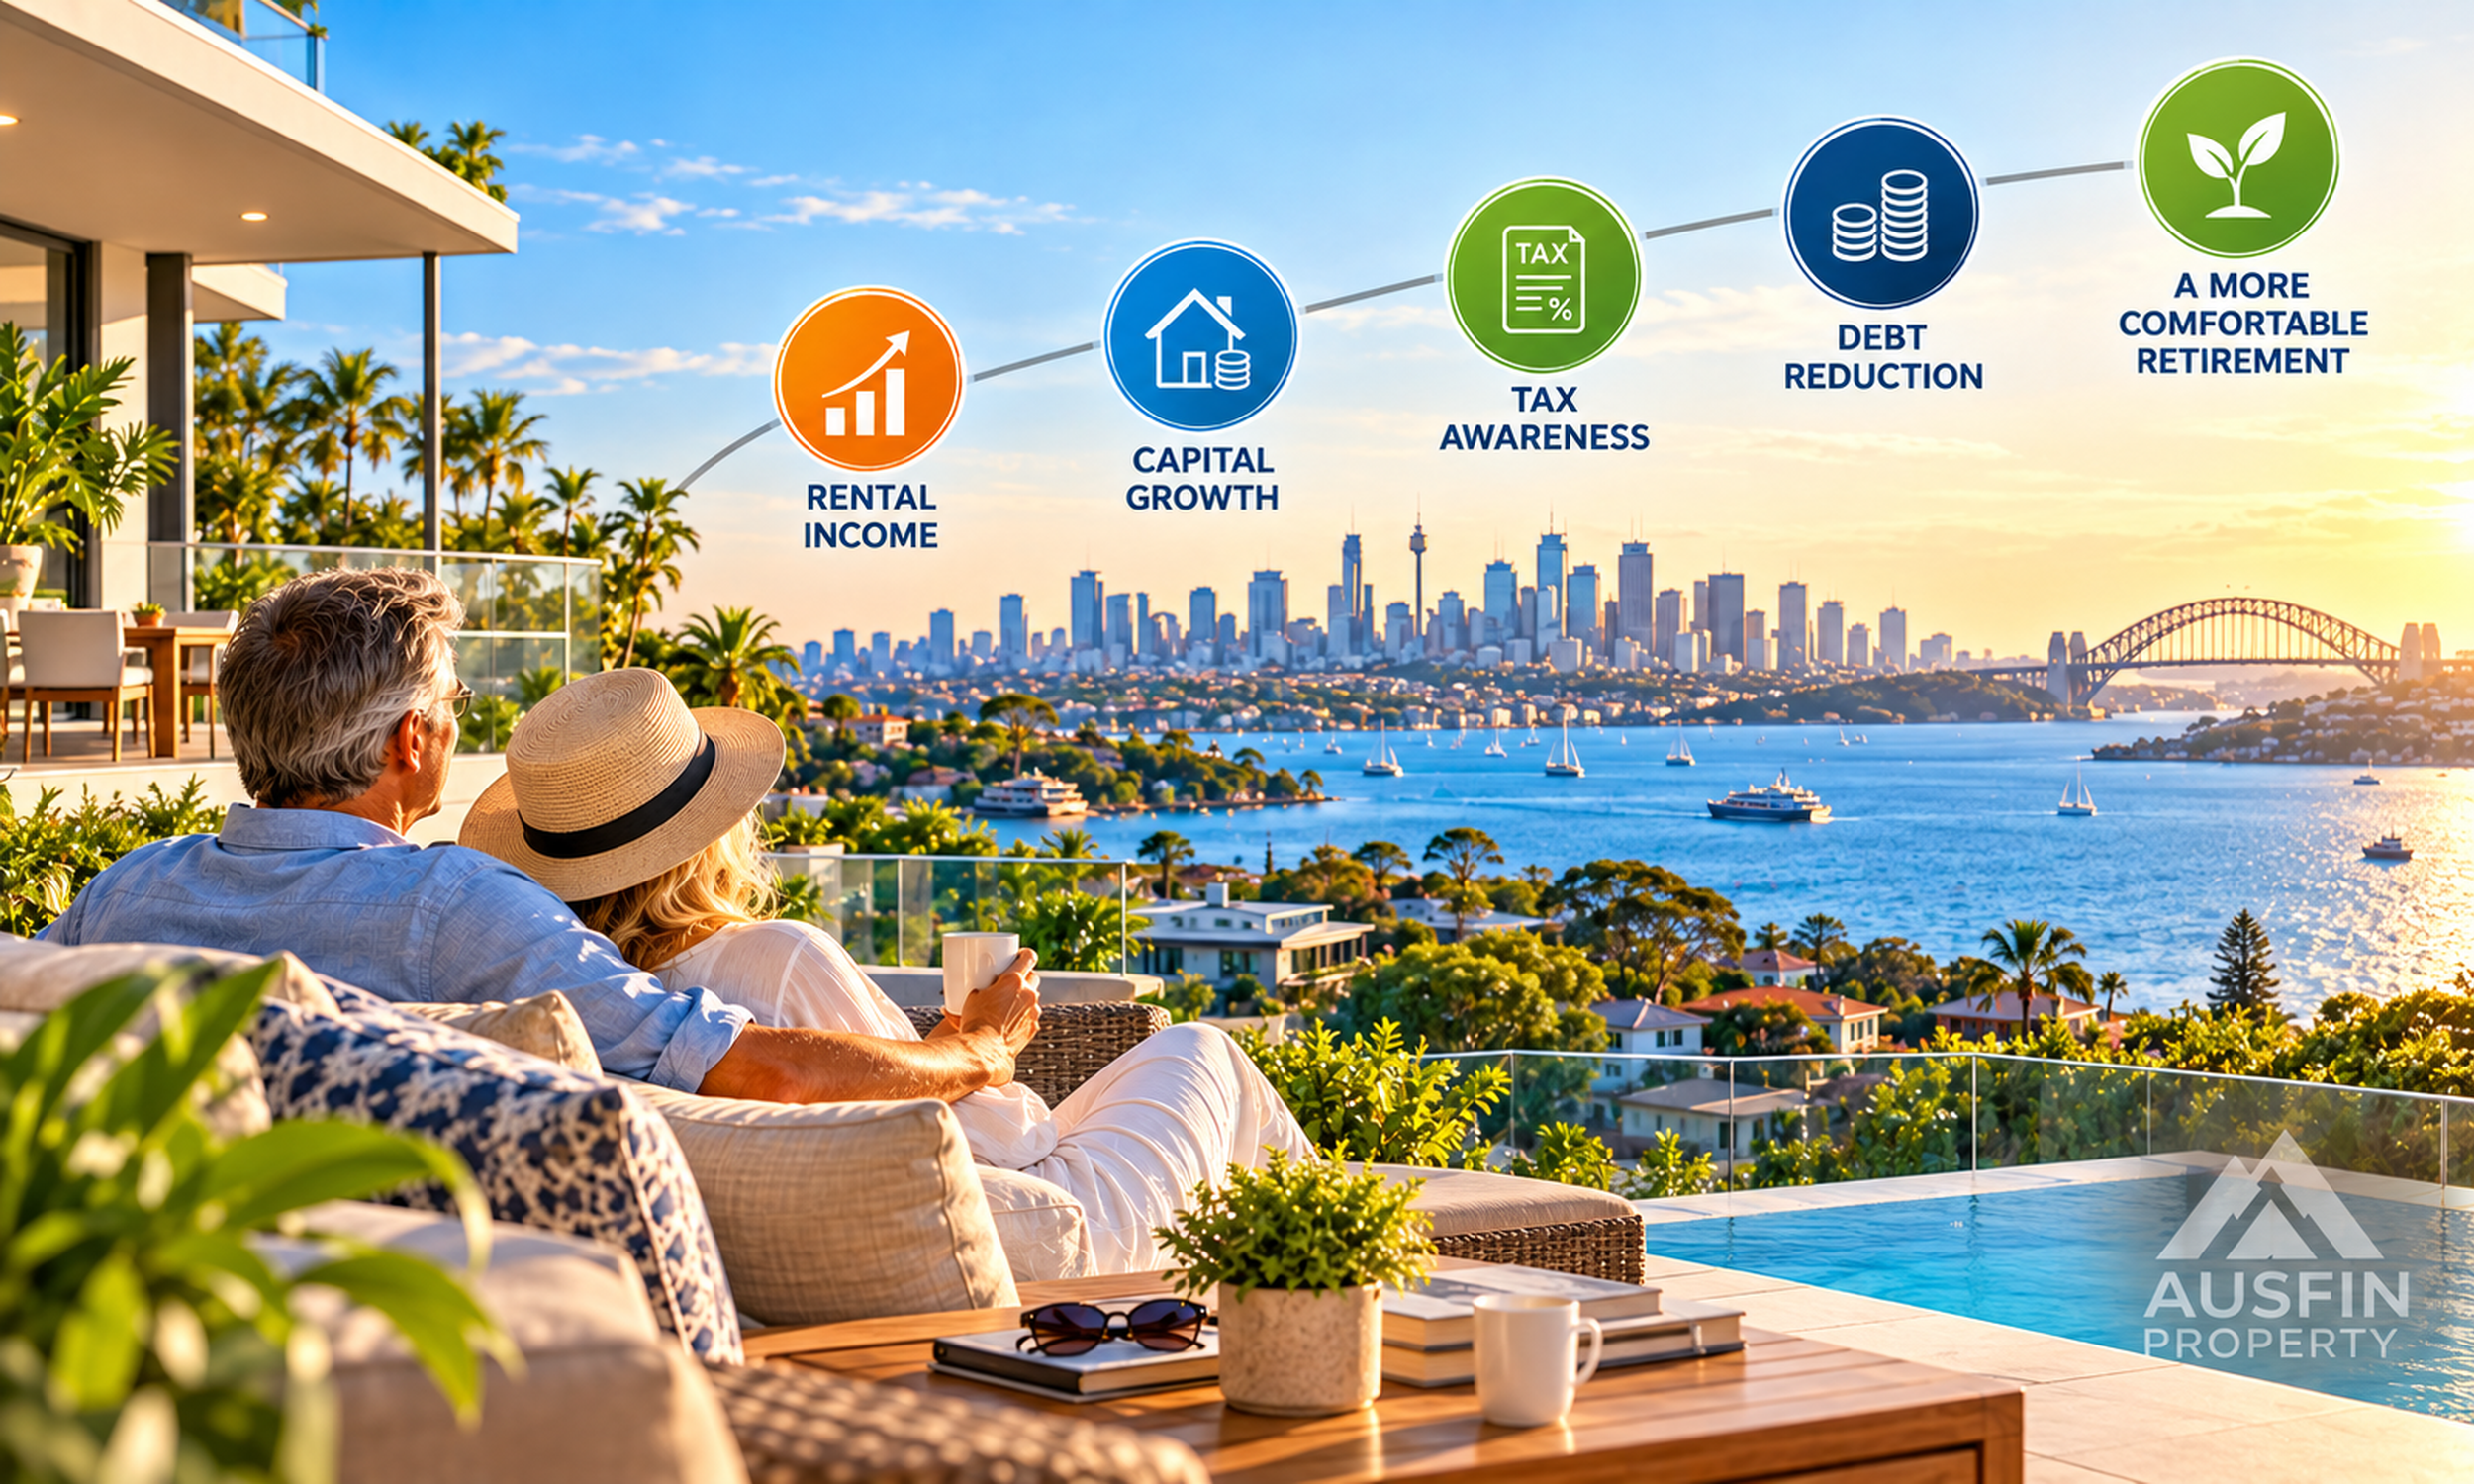
Property can play a valuable role in retirement planning. However, a successful strategy needs more than buying a property and hoping prices rise. Australians who retire comfortably with property usually focus on cash flow, debt reduction, tax awareness and risk management from day one.
In other words, property should support your lifestyle. It should not create a retirement burden.
First, estimate what comfortable retirement looks like for you. Consider everyday spending, travel, healthcare, home maintenance, insurance and unexpected costs. Then compare that figure with your likely superannuation income, Age Pension eligibility and other investments.
Property may help fill a gap through rental income, capital growth or a later sale. Yet investors should assess the full picture. Moneysmart notes that retirement income commonly combines super, the Age Pension, savings and investments. It also encourages Australians to consider the costs, tax effects and benefit impacts before keeping or selling an investment property.
Therefore, set a clear target before you search. For example: ‘I want my portfolio to produce $X per year after property costs and debt repayments.’
Capital growth matters. Nevertheless, income often matters more as retirement approaches.
A high-growth property may look attractive on paper. However, it can still strain your budget. Thus far, rent needs to cover a meaningful share of interest, rates, insurance, management fees, repairs and land tax. Instead, calculate the expected net income.
Use this simple formula:
Net rental income = annual rent − vacancy − management − rates − insurance − maintenance − loan costs − tax
Hence, calculate gross rental yield:
Gross rental yield = annual rent ÷ purchase price × 100
For instance, $650 weekly rent equals $33,800 a year. On a $700,000 property, the gross yield equals about 4.8%. Yet gross yield does not show your real return. Consequently, always allow for vacancy, repairs and finance costs.
Australian investors can begin research on major listing and data platforms, including realestate.com.au, Domain and property.com.au. Realestate.com.au offers listings, sold-property information and suburb research. Domain provides suburb profiles, auction results and market tools. Meanwhile, property.com.au aggregates publicly available property information and data-provider inputs to help users research individual homes.
These platforms help investors shortlist areas. However, no portal can replace due diligence. Alternatively, you can engage a Buyer’s Agent to streamline the process.
Compare several sources. Then check recent comparable sales, local rental listings, days on market, vacancy conditions, flood exposure, strata records, zoning and planned infrastructure. In addition, speak with a local property manager. They can test whether an advertised rent matches tenant demand. Consequently, a competent Buyer’s Agent can compile all these for you.
A useful decision algorithm looks like this:
This process reduces emotion. Moreover, it makes each purchase easier to measure against your retirement plan.
Debt can help investors build assets. Still, debt can also magnify risk.
Interest rate changes, vacancies or major repairs can quickly reduce income. Therefore, build a cash reserve and test your position at a higher interest rate. Ask: ‘Could I still hold this property if rent stopped for several months?’
As retirement gets closer, many investors focus on reducing debt. A lower loan balance can turn more rental income into usable income. Conversely, relying on constant refinancing or future price growth can leave retirees exposed when lending conditions tighten.
Tax rules can influence returns, although tax benefits should never drive the entire decision. The ATO explains that rental income is assessable and that investors may claim eligible expenses. However, some costs must be claimed over several years, while capital or private expenses may not qualify as immediate deductions. See the ATO rental-property guide.
Property can also affect Capital Gains Tax, superannuation decisions and Age Pension eligibility. For example, an investment property generally counts under the assets test, while the home you live in receives different treatment. Accordingly, seek advice from a licensed financial adviser and registered tax professional before you buy, sell, transfer or move property into an SMSF.
Finally, avoid placing every retirement dollar into one property or one suburb. Property can take time to sell. It can also require unexpected cash.
Keep accessible savings. Diversify where appropriate. Review rents, costs, insurance and debt at least yearly. Most importantly, buy property because it strengthens your retirement income plan—not because a headline promises quick wealth.
Property investing can support a comfortable retirement. With disciplined research, realistic cash-flow modelling and a long-term mindset, it can become a useful part of a broader Australian retirement strategy.
Quick Answer: Is There Magic in Property? Real estate builds wealth through measurable forces rather than magic. Industry estimates Australian...
Read More
New Build Property Investment is the smart choice in Australia. The government wants more new homes. Therefore, in the 2026-27...
Read More
Australia’s rental crisis is deepening in 2026. Discover the latest vacancy rates, rent trends, and what smart property investors should...
Read More